Filter by Member

Filter by Member Directory

Categories

Filter by Category
As geopolitical tensions reshape global trade, payment sovereignty is emerging as a strategic priority, prompting countries to rethink control over financial infrastructure.
For payment and e-money firms, FCA authorisation is more than a checklist: the application signals judgement, competence and regulatory readiness.
As AI accelerates cyberattacks and fraud, payments firms need network-wide intelligence to assess trust and stop threats before settlement.
Chargeback costs are rising as friendly fraud grows, with merchants increasingly passing the financial impact of disputes on to consumers.
Agentic payments may be advancing rapidly, but scalable adoption depends on reconciliation that can prove what agents did, and why.
Trusted, interoperable payments infrastructure will be critical to UK competitiveness as stablecoins, AI and global money movement evolve.
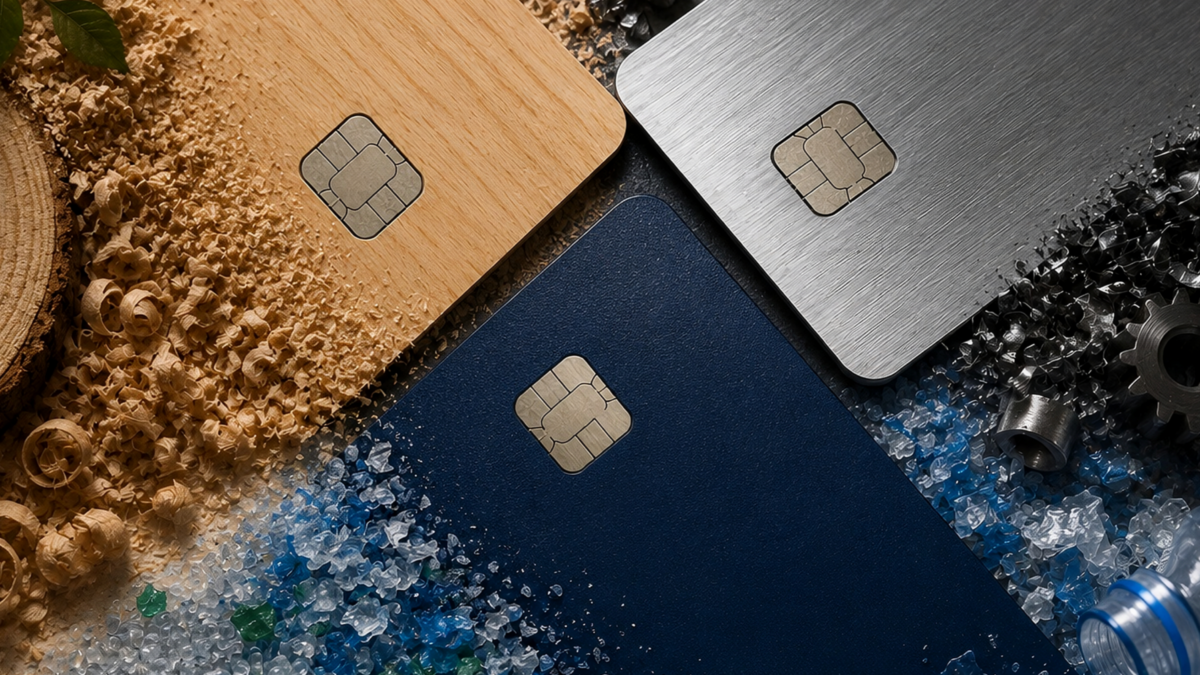
New Copecto research suggests wooden payment cards could challenge metal in premium banking, combining exclusivity with sustainability.
The FCA’s Mills Review explores how AI and agentic finance could reshape UK retail financial services, regulation and supervision by 2030.
The UK’s digital ID scheme may be gone, but the debate over trusted digital identity, financial inclusion and payments is only just beginning.
New research shows document fraud is becoming more sophisticated, prompting payment providers to strengthen onboarding controls and fraud detection.
New research suggests UK merchants value fast settlements, security and transparency over flashy innovation, challenging payment providers to focus on business fundamentals.
As cyber threats evolve, AI-powered anomaly detection is becoming essential for helping payment firms identify threats early and strengthen resilience.
New FRC guidance is reshaping CASS 15 safeguarding audits, with payment and e-money firms urged to strengthen controls, documentation and audit readiness before May 2026.
KYC is evolving beyond onboarding. As fraud grows more sophisticated, payments firms are shifting towards continuous, risk-based identity verification.
For SMEs, cash remains essential for resilience, liquidity, and inclusivity as digital payments still bring costs, delays, and dependency risks.
Digital wallets, open banking, and instant payments are reshaping competition as banks fight to retain customer ownership and engagement.
Cross-border payments remain costly and unpredictable for SMEs, despite advances in payment technology and real-time infrastructure.
Fraud is not just financial loss but a confidence shock, driving lasting behavioural change, eroding trust, and quietly slowing digital finance adoption.
Ahead of 7 May 2026, payments firms face a shift from deadline compliance to sustained FCA scrutiny, with data-driven supervision set to reshape outcomes.
European Securities and Markets Authority oversight signals a shift for EMIs, as standardised reporting demands stronger data infrastructure, governance, and technical readiness.
Agentic commerce is emerging as a payments strategy, with banks expected to provide trusted execution, controlled delegation, and robust fraud and consent safeguards.
Poland is emerging as a credit innovation hub, shifting from product-led lending to real-time, embedded credit driven by digital behaviour and transaction data.
Instant payments aren’t a compliance exercise. They demand real-time infrastructure, and EMIs that treat them as strategic will outpace those that don’t.
EMIs are rethinking treasury as rates rise. LVNAV money market funds offer FCA-aligned liquidity, diversification and yield beyond traditional bank deposits.
Customer screening is central to FCA-regulated onboarding, but phonetic matching and fuzzy search limits mean firms must test tools carefully to avoid missed risk signals.
Banks face a growing talent crisis as legacy system experts retire and younger engineers reject outdated tech, making core modernisation a workforce priority.
UK e-commerce is maturing fast, pushing banks to support both cards and open banking. Success will depend on orchestration, fraud control, and modern acquiring infrastructure.
A balanced assessment of Europe’s payments market highlights continued growth alongside rising fraud, cost pressures, regulatory complexity, and strategic uncertainty.
UK BNPL faces FCA regulation from 2026, requiring affordability checks and greater transparency, reshaping provider models, merchant partnerships, and embedded finance.
An analysis of why legacy AML systems are failing in real-time payments, and how flexible, risk-based and collaborative compliance platforms can support sustainable growth.
Payments profitability now depends on transaction-level visibility. Blended pricing hides losses, and analytics, not regulation, is the real lever for control.
Identity fraud is now a core payments infrastructure. AI-driven impersonation, real-time liability and continuous checks are defining how UK fintechs scale safely.
UK payments in 2026 will balance smarter digital wallets, AI-led commerce, VRPs and sustainability with resilience, cash access, regulation and trust.
Agentic AI promises seamless automated payments and hyper-personalised retail, but growth depends on new trust, fraud models and rules for autonomous agents.
Payment fragmentation drains resources and slows growth. A unified payment ecosystem cuts complexity, reduces costs, and gives digital businesses the clarity needed to scale.
Fraud is rising fast and criminals are using AI at scale. UK banks must modernise to real-time, unified fraud and AML defences or risk regulatory, financial and trust failure.
Banks are eager to adopt AI, but payment network compliance is too complex and risky for generic models. Purpose-built solutions avoid data, context and validation pitfalls.
The EU Digital Identity Wallet will reshape verification across Europe, offering new assurance for PSPs, but rollout will be uneven and businesses must prepare for varied adoption.
Agentic AI is reshaping how payments work, creating huge opportunities but forcing providers to adapt fast as new protocols, risks, and standards emerge.
UK fraud controls have reduced domestic APP scams, but criminals are shifting to smaller institutions and cross-border channels, making consortium data vital for defence.
As payments become faster and more digital, the industry must balance efficiency with empathy—humanising technology to rebuild trust and real connection.
LSEG highlights how rising fraud and new EU rules are reshaping payments, calling for stronger data, technology, and collaboration to rebuild trust across the ecosystem.
As fraud detection grows more complex, explainable AI is becoming essential—helping banks ensure transparency, speed investigations, and meet rising regulatory demands.
B2B payments are being reshaped by orchestration, automation, and embedded finance, enabling faster, smarter, and more scalable global transactions for businesses.
By 2050, payments will be intelligent, autonomous, and embedded in daily life, powered by AI, quantum infrastructure, and trust-driven digital ecosystems.
Stablecoins are evolving from speculative assets into practical tools linking traditional finance with blockchain. Regulation and infrastructure now drive their mainstream adoption.
AI and smart routing are transforming payments from a back-office function into a strategic advantage, driving efficiency, resilience, and better customer experiences.
The issuing model is overdue a rethink. Discover how Holistic Issuing replaces fragmented setups with a unified, agile, and cost-efficient approach.
Fraud has evolved from clumsy scams to AI-powered campaigns. This piece explores why cyber and fraud defences must now fuse into one fabric.
UK fraud losses hit £1.17bn in 2024. With AI fuelling attacks, this piece explores how banks can harness AI to defend payments and restore trust.
Firms seeking FCA Authorisation must ensure consistent business plans, permissions, and SMF roles to avoid delays, rejection, and regulatory concerns.
Synthetic identity fraud is rising fast, with deepfakes and AI-driven crime exposing gaps in global AML/KYC. New defences are urgent.
Card issuing is shifting from plastic to tokenisation, APIs, and embedded finance. Incumbent banks must modernise or risk being left behind.
Card networks still dominate UK retail, but QR + open banking is breaking through—faster, cheaper, and reshaping the high street.
APP fraud is rising fast in the UK; new rules, verification tech and 24/7 risk monitoring are key to shifting from reaction to prevention.
By 2030, payments will be instant, decentralised, and invisible—blending cashless systems, CBDCs, and blockchain into global infrastructure
The UK must act fast on open, global crypto rules to lead in digital assets, boost stablecoin use, drive tokenisation, and spur economic growth.
European financial institutions face rising fraud, regulatory pressure, and compliance fatigue—modernisation is now essential for resilience and risk reduction.
UK card issuers must modernise platforms, prioritise digital experiences, and embrace innovation to meet rising expectations and compete in a rapidly evolving market.
Unlock global growth with smart localisation, seamless payments, and trusted partners, build customer-first experiences that convert across borders.
Explore how AI is transforming Fintech customer support, enhancing efficiency, enabling personalisation, and preserving essential human touch.
SMEs that modernise payments can unlock growth, improve cash flow and build trust—while those that delay risk revenue loss and reputational damage.
Embedded finance is no longer optional—it’s how brands remove friction, retain users, and unlock new revenue streams without added regulatory burden.
APP fraud cost the UK £450m in 2024. With scams starting online, debate grows on who should bear responsibility for prevention.
Virtual cards gain momentum in Q3 as merchants seek faster, safer, and more scalable ways to manage business spend and streamline payments.
PSPs that embrace automated, API-first onboarding can turn compliance from a bottleneck into a strategic growth driver—faster, smarter, and globally scalable.
AI agents are reshaping payments. Learn how tokenisation and cloud-first infrastructure are unlocking the next era of autonomous digital commerce.
As sustainability gains ground, card issuers and payment providers are exploring practical strategies to meet ESG goals and shifting consumer expectations.
Survey reveals global firms lose nearly $100 million annually to financial process inefficiencies, driving investment in AI, cybersecurity, and embedded finance.
Exploring how corporate cards, when issued through specialist providers, offer enhanced control, efficiency, and insight for business expense management.
As digital wallets evolve, the real opportunity isn’t in doing everything—it’s in doing what matters, exceptionally well, for today’s users.
As instant payments become the norm, true finality is essential to ensure trust, reduce fraud risk, and protect the integrity of global payment systems.
As AI agents emerge in commerce, the payments industry must rapidly adapt infrastructure and governance to enable secure, autonomous transactions.
AI is transforming compliance in financial services, offering efficiency gains while introducing new risks that demand robust governance.
As digital payments evolve, AI is reshaping fraud prevention with real-time insights, adaptive controls, and improved security across financial systems.
Modern payment orchestration platforms now serve as strategic infrastructure—optimising performance, compliance, and customer experience at scale.
Cross-border payments remain costly and complex, but innovations in FX, APIs, and stablecoins are unlocking faster, smarter global money movement.
Real-time payments and integrated tools are reshaping how SMEs manage operations, adapt quickly, and deliver seamless customer experiences.
As APP fraud grows more sophisticated, banks must move beyond transactional checks and use behavioural signals to intervene before money moves.
As digital payments outpace plastic, UK banks must modernise card infrastructure or risk losing relevance to faster, cloud-native challengers.
Open banking and instant payments are reshaping how regulated sectors manage compliance, onboarding, and real-time money movement at scale.
As financial crime evolves, correspondent banks must prioritise wire transfer transparency to meet global regulations and safeguard the financial system.
AI is reshaping fintech marketing—enabling personalisation, predictive targeting, and compliance—while raising new ethical and strategic questions.
SMEs drive the UK economy, but many still face barriers to essential financial services. Closing the gap requires more than lending—it needs infrastructure.
As the payments job market shifts from growth to efficiency, firms must rethink hiring strategies to compete in a saturated, high-stakes landscape.
Consumers expect speed and transparency—banks are responding with self-service tools that streamline dispute resolution and enhance trust.
QR code payments offer UK small businesses a fast, low-cost alternative to card terminals—boosting cash flow and meeting modern customer expectations.
Tokenisation is reshaping financial services, offering faster, more efficient ways to manage and trade assets across bonds, real estate, and beyond.
SEPA Instant promises faster, 24/7 payments across Europe, but with few banks ready, urgent investment is needed to meet rising demand and regulatory deadlines.
To address the money mule problem, organisations must combine elements of fraud prevention, cyber threat intelligence, and anti-money laundering capabilities.
Fintech automation brings speed and innovation, but system failures, outages, and over-reliance highlight the need for strong oversight and planning.
Embedded finance and multi-banking give corporates greater control, new revenue streams, and stronger networks—unlocking value beyond traditional banking.
With consulting revenues soaring, choosing the right partner means defining objectives, setting scope, and avoiding solutions that miss the mark—or your watch.
The payments landscape is evolving with digital assets, real-time transactions, and new regulations—businesses must adapt to stay efficient and compliant.
Banks clinging to outdated systems risk security breaches, regulatory headaches, and lost market share—modernisation isn’t just an upgrade, it’s a survival strategy.
Legacy systems are a competitive risk—financial institutions must modernise with AI, automation, and cloud solutions to stay agile and scalable.
AI-driven fraud is evolving fast—banks must adopt adaptive AI models to detect and prevent scams in real-time.
With AiTM fraud rising, businesses must strengthen security, adopt biometrics, and educate users to stay ahead.
E-invoicing is transforming financial operations, enhancing efficiency, compliance, and fraud prevention while shaping the future of digital tax systems.
Forex brokers must adopt payment orchestration, real-time settlements, and AI fraud prevention to stay competitive and compliant.
Personalised, omnichannel payment experiences are key to deepening loyalty, boosting retention, and exceeding customer expectations.
The future of e-commerce is subscription-based, offering businesses predictable revenue, deeper customer relationships, and long-term growth.
The future of payments is digital, inclusive, and transformative—driving financial access, innovation, and global economic empowerment.
Open finance is redefining data sharing, innovation, and growth in financial services.
Travel is surging, but outdated payments lag—fintech-driven innovation is key to seamless, secure, and sustainable transactions.
In 2025, payments firms must prioritise safeguarding funds, expanding open banking, and preparing for stablecoin regulation to stay competitive and compliant.
Open banking holds promise for e-commerce, but its success depends on targeted use cases, merchant incentives, and consumer trust.
Mobile payments and digital wallets are driving a cashless economy, reshaping commerce, and redefining consumer expectations.
UPI is transforming cross-border payments, boosting India’s global digital payment reach.
With fraud evolving faster than security, banks must embrace risk-based authentication or risk falling behind.
The EU’s shift to open banking and finance presents both opportunities and challenges, demanding a balance between innovation, security, and regulation.
As crypto reshapes finance, the FATF’s Travel Rule struggles to keep pace—can global regulators close the gap on illicit transactions?
Many payment firms assume they need an FCA licence, but exemptions may allow them to operate with fewer regulatory burdens.
The 2024 holiday shopping season set eCommerce records, but a surge in post-holiday returns and chargebacks highlights the costly “holiday hangover” for merchants.
Network tokenisation boosts security, cuts costs, and enhances customer experiences, making it essential for modern merchants.
Swift drives global interoperability and innovation, aligning with the UK’s National Payments Vision to enhance seamless, secure payments.
The payments industry in 2025 will see advancements in real-time payments, AI tools, and voice-activated technologies reshaping consumer and business interactions.
Fintech is leading the shift from traditional IPOs to transparent, cost-effective direct listings.
Digital payments demand advanced fraud prevention, blending AI and human intelligence to counter evolving threats while ensuring seamless user experiences.
2025 payment trends focus on digital wallets, instant payments, AI, fraud prevention, and consumer convenience, driven by evolving regulations and innovation.
De-risking endangers financial inclusion, driving MSBs out and boosting unregulated markets, calling for urgent reform.
Rising youth involvement in economic crimes highlights the urgent need for robust financial education.
UK businesses must prioritise digital investment to boost financial clarity, agility, and competitiveness in an evolving economic landscape.
Fintech drives UK SME growth with tailored solutions, streamlining finances and boosting efficiency.
Web3 is transforming finance with blockchain, digital assets, and smart contracts, paving the way for a decentralised future.
Quality Engineering is transforming digital banking, enabling seamless innovation, operational continuity, and future-proofing in a rapidly evolving landscape.
In an era marked by technological advancements and evolving consumer preferences, high-end banks and financial institutions are constantly seeking for innovative ways to cater for the demands of the discerning mass affluent market.
Open Banking set out to revolutionize finance by giving third-party providers access to customer data (with consent) to drive innovation and empower consumers. But while Europe’s PSD2 regulation has enabled new fintech services and a vibrant TPP ecosystem, adoption has fallen short of initial expectations. Complex regulations, security concerns, and, most critically, profitability challenges for banks have created hurdles. Discover how a shift in strategy, combined with data enrichment, could help banks embrace Open Banking as a growth opportunity rather than a regulatory burden.
AI transforms payment routing, boosting success, cutting costs, and improving customer experiences in real time.
A flexible, focused marketing plan improves budgeting, targeting, and adaptability, with ongoing analysis ensuring effective growth.
Compliance in payment communications is key to trust; AI solutions and customised frameworks ensure secure, global adherence to regional regulations.
The Click to Pay mandate allows card issuers to modernise payments, boost customer experience, and ensure secure, interoperable digital transactions.
The Payments Association (TPA)’s George Iddenden recently sat down with Peter Theunis, senior vice president sales and European managing director at BPC to discuss the remarkable transformation of the payments processing industry, driven by the rise of fintech, the shift towards digital payments, and evolving consumer behaviours.
Chargeback abuse costs billions, but merchants can reduce fraud with proactive strategies like customer engagement and better security.
Visionary leadership is crucial for driving innovation and navigating the rapid changes in the payments industry.
Traditional banks must modernise their tech stack to stay competitive with fintechs and meet shifting consumer expectations.
Despite the growth of digital payments, cash use is rising in the UK, supported by emerging cashtech innovations.
The merged R&D tax credit scheme in April 2024 introduces new rules for contracted-out R&D, benefiting larger businesses but requiring careful planning and documentation.
Rising maintenance costs in social housing, driven by damp remediation and regulations, are pushing providers to adopt preventive strategies and modernisation.
How open banking can reshape finance, enabling personalised services, streamlined verification, and improved fraud detection.
The challenges financial institutions face under SEPA Instant Credit Transfer regulations and explores how advanced technologies can help overcome them.
Discover how moving sales online can transform your business and unlock new growth opportunities.
In the fast-moving payments industry, trust must be replaced by a “Protection Model” focused on safeguarding compliance, technology, and risk management.
Payment companies are accelerating KYB with AI and APIs, enhancing onboarding speed and competitiveness while maintaining strict compliance.
The fintech industry remains male-dominated, but fostering mentorship, challenging stereotypes, and supporting gender equality initiatives can pave the way for more women to rise into leadership roles and create a more inclusive future.
Choosing the right custody solution is vital for institutions to securely navigate the evolving digital asset landscape and future-proof their financial operations.
Outsourcing customer support allows companies to focus on growth while ensuring high-quality service through experienced partners who personalise solutions, maintain brand consistency, and leverage advanced technology.
The payments industry must address cross-border inefficiencies to support SMEs, which are critical to global economic growth and financial inclusion.
Cross-border payments expand a business’s global reach, but their success hinges on secure, efficient processes, versatile payment methods, and strong partnerships with payment providers who offer seamless integration and robust fraud protection.
Digital wallets are reshaping payments with convenience and security, but face challenges like device reliance and regional limits; with increasing regulatory focus, their growth and innovation are set to continue.
Banks must quickly adapt to ISO 20022, leveraging strategic partnerships to overcome legacy system challenges and meet the March 2025 compliance deadline.
The shift from virgin PVC to recycled PVC (rPVC) and paperboard payment cards is revolutionising the financial industry, reducing environmental impact while offering business advantages, and positioning financial institutions as leaders in sustainability.
Rethinking the approach to banking silos, this article explores how connecting, rather than breaking down, silos can foster innovation and efficiency in financial institutions.
Despite significant advances, cross-border payments still face challenges like delays, high costs, and inefficiencies, but innovative projects like BIS’s Project Rialto and Nexus offer hope for a more seamless global payment system.
Fintechs can accelerate mainstream adoption of digital assets by integrating them with traditional payment networks, enabling seamless everyday transactions.
The move to ISO 20022 brings benefits like enriched data and improved fraud prevention, requiring a strategic approach and decisions between building in-house solutions or partnering with vendors.
With the UK at the forefront, the future of cross-border payments is being shaped by technological advancements, regulatory changes, and the growing demand for efficient, secure, and cost-effective solutions.
UK banks’ reduced lending and account closures stress SMEs, highlighting the need for multi-service apps (MSAs) to streamline financial services with open banking.
Swift’s updated CSP and IAF are essential for ensuring robust cybersecurity and compliance across the global banking community.
Card issuer processors face integration, compliance, and fraud challenges but can stay competitive by streamlining processes and enhancing customer experiences.
Navigating the complexities of global expansion in fintech requires strategic partnerships, innovative solutions, and a deep understanding of regional regulatory and cultural nuances.
How modernising legacy systems through outcome-driven strategies, cloud migration, and fintech partnerships enhances agility and innovation.
Open banking revolutionises financial services by enhancing user experience with seamless account integration, real-time transactions, and personalised services.
APP fraud is surging, with UK Finance reporting £42.6 million lost in early 2023, prompting calls for stronger consumer protections.
Combining digital innovations with traditional in-person services allows banks to provide a seamless experience that leverages the convenience of digital services and the personal touch of physical interactions.
Utilising payments data analytics can drive financial growth by enhancing services, reducing costs, and improving security, though it requires overcoming challenges in data management, integration, and fraud prevention.
PSD3 updates PSD2 to enhance electronic payment services, merging payment and e-money institutions, regulating digital marketplaces, clarifying delegated authentication, and detailing open banking API requirements
The financial sector must modernise card issuance to meet consumer demand for instant, seamless payments, with digital platform-issued cards projected to reach 1.3 billion by 2027, driven by API-led approaches and the rise of digital wallets.
From 7 October this year, all consumers who are victims of automated push payment (APP) fraud paid via faster payments must be reimbursed within 5 business days, with the cost split equally between the paying and receiving payment service providers (PSPs)
The UK leads the open banking revolution, driven by the Payment Services Regulations and the revised PSD2, fostering competition, innovation, and secure data access, with significant adoption growth and benefits for businesses and consumers alike.
Fintech firms must leverage personalized and secure communication tools, like SMS and chat apps, to build consumer trust and enhance customer experience, as demonstrated by successful partnerships with reliable providers.
Global SMEs are shifting to fintechs for their financial needs, urging traditional banks to collaborate with fintech providers to offer flexible, innovative solutions, writes James Camilleri, CEO and co-founder of Fyorin
ChatGPT, nearing 200 million users, uses Large Language Models to streamline tasks and improve efficiency in industries like fintech, enhancing customer support and fraud detection.
In 2023, the UK government committed £100 million and 400 new fraud officers to reduce fraud by 10% by 2025, amid increasing social media and deepfake scams, according to IDnow’s UK Fraud Awareness Report.
As real-time payment adoption grows, 50% of European firms are already involved, with another 42% planning to join, highlighting the balance of challenges and benefits in managing financial crime.
Instant payments are rapidly transforming the transaction landscape, supported by a global increase in payment rails and advanced services, despite facing challenges from fraud and regulatory demands.
Unveiling the complexities and optimisation opportunities in the card payments industry’s operational landscape.
PSPs must enhance their end-to-end reconciliations to deliver seamless, efficient payment services and stay competitive in the rapidly evolving fintech landscape
Financial inclusion, as defined by the World Bank, is crucial for economic development and social progress, ensuring equal access to financial products and services tailored to the needs of both individuals and businesses. The United Nations emphasises financial inclusion as a crucial driver of economic and social development, evident in its inclusion as component eight of the 17 Sustainable Development Goals for 2030.
In an increasingly interconnected world, global commerce has become the lifeblood of the modern economy. Businesses of all sizes are expanding their reach beyond borders, opening up new opportunities and markets. However, the traditional financial systems have often lagged behind the speed and efficiency demanded by the globalised marketplace. Enter cross-border real-time payments—a concept that is reshaping international trade by breaking down barriers and providing a boost to global commerce.
In the first half of 2023, UK Finance reported authorised push payment (APP) fraud losses amounting to £293.3 million, with the total number of APP cases increasing by 22%. The nature of authorised push payment (APP) fraud was harrowing – victims were willingly initiating and authorising payments into controlled accounts, often driven by criminal manipulation or misinformation.
2023 research by American Express reveals that late payments are a significant challenge for UK finance professionals, driving a shift towards digitizing B2B payments to improve efficiency and cash flow.
As the pace and scope of cross-border payments continue to accelerate, it’s becoming increasingly clear that the payment industry’s approach to compliance must also evolve—and take centre stage. 
Banks and finserv companies have a significant task in 2024 when it comes to building and retaining consumer trust. This is concerning news because it’s easier than ever for customers to switch banking providers.
Traditional finance is at a crossroads with the new digital frontier, and the rapidly evolving landscape of digital assets demands innovative custodial solutions. For banks, payment service providers, financial institutions and others that are either considering or already piloting digital asset projects, it’s imperative to understand the importance of an underlying custody infrastructure.
Disability has the potential to impact anyone in society. It can be visible or hidden, temporary, or permanent, and can be influenced by a number of factors. More than one billion people around the world have some level of disability, equating to roughly 15% of the global population. At the same time, the world is ageing as people live longer, and the number of people aged 60 and over will double to 2.1 billion by 2050.
The payments sector’s success and growth over the past decade can largely be attributed to firms’ ability to meet and exceed customer’s expectations. Unlike established banks, fintechs are largely free from the legacy tech stacks that slow down banks from modernising. So Payment Service Providers (PSPs) can anticipate customer needs and provide services that address their problems. However, as new PSPs continue to emerge, the landscape is becoming increasingly competitive. So PSPs have to meet changing customer expectations more quickly.
The ongoing digitisation of payments can perpetuate a false narrative that traditional payment cards are becoming obsolete. The reality is that card payments are thriving globally, adapting to the new age of fintech and smartphones. While the landscape of financial transactions is ever-changing, the truth is that one size does not fit all – and different markets have different payment requirements. 
Open banking — a promised financial utopia where data flows freely, consumers reign supreme, and businesses can reduce their payment processing fees — but what use is this powerful innovation if you can’t get customers to actually adopt it?
December 2023
After a year of development, the royal assent of the UK Financial Services Markets Act (FSMA 2023) signifies that change is on the horizon for the UK’s financial landscape and its players.
Can FI’s look beyond transaction data to uncover the true picture of risk? ComplyAdvantage’s research revealed that payment screening teams continue to grapple with siloed data sets and disparate systems. And yet, as the financial crime landscape grows more complex, the need to connect fragmented data sets to understand the global networks behind financial crime has never been more important. ComplyAdvantage’s Iain Armstrong give his top tips for integration success in payment screening.
Guy W. Lecky-Thompson, head of products & processing services at Trionis explains why ATMs still have a prominent role in the future of the payments industry.
Tony Petrov, chief legal officer at Sumsub, summarises the rules incorporated in the EU Artificial Intelligence Act (EU AI Act) and how they might impact on the industry.
The transition to real-time payments is well underway. AutoRek global payments manager, Nick Botha, explains why those who prepare and adapt now will be better poised to become a leader in the world of real-time payments.
Sumsub, a full-cycle verification platform, releases its ‘State of Verification and Monitoring in the Crypto Industry 2023’ report. Polina Uzhva, partner marketing manager, Sumsub, provides a summary, focusing on the regulations and verification practices for crypto companies, with highlights from verification performance and identity fraud statistics.
Eduardo Martínez of Toqio outlines why embedded finance has become an essential component of developing systems and providing customer satisfaction.
Christien Ackroyd explains how the ethical grade concept works, covering best practices, benefits, and which banks are getting it right.
Pavlo Khropatyy explains how banks should embark on the journey of digital transformation, keeping their customers firmly at the heart of their strategies.
October 2023
With big tech entering the banking space, payment firms need to be at the forefront of changing the ‘software sabotage’ culture to ensure consumers and those in the supply are protected as well as reducing e-waste.
James Hunt of Feedzai discusses the evolution of acquiring banks and PSPs.
Open banking can address customer pain points from bill paying to shop checkouts, but consumers need reassurance to use it with confidence, says Holly Coventry, vice president, international open banking payments at American Express.
UK regulators are prioritising APP scam prevention after £480 million in customer losses in 2022, proposing new PSR rules for stricter fraud warnings and reimbursements, especially protecting vulnerable customers and small businesses
Monica Eaton explores how augmented reality is used in the marketplace and what impact it might have on the payments industry. 
Daniel Holden explains the meaning and significance of unified commerce and why it is vital to the customer experience.
FIS senior sales executive Julien Farley discusses why he believes that the payment industry should adopt a more open-minded approach to the different payment methods that are used worldwide.
Eduard Stringer, director of product management for Europe at FIS, explains why he believes the EU needs to step up and ensure regulation supports the needs of payments businesses and consumers.
Autumn 2023
It will make millions of us redundant. It will turn whole industries upside down. It might even lead to the obliteration of humanity, and its replacement with something smarter and more civilised.
Bob Kaufman explains how integrated payment frameworks transform reconciliation processes for travel and tourism businesses.
August 2023
In the last seven years, Tillo has grown from a start-up with a handful of employees to a multi-national company employing nearly one hundred individuals across three continents.
Russel Fernandes, head of product for card present payments at Trust Payments shares his 11 tips to make sure companies get the most out of their point-of-sale (POS) systems.
July 2023
The Joint Regulatory Oversight Committee’s (JROC)’s open banking recommendations have the potential to revolutionise payments, but big investments will be necessary into digital transformation, legacy platform modernisation and cloud migration that is future-proof.
Autumn 2023
Chargebacks911’s Monica Eaton examines five ways how businesses can utilise bots and new technology to drive sales online.
With innovation in B2C payments growing at much faster rate, Intellias’s Olaf Baunack debunks the myths associated with B2B payments.
Sean Forward at payabl. explores how the industry could see a rise in M&A activity and a consolidation of businesses and services.
With more and more young people using BNPL as a payment option, Monica Eaton of Chargebacks 911 explores the benefits and risks of using this type of lending to make purchases.
AutoRek’s Nick Botha discusses how the FCA is taking payments safeguarding very seriously and firms should be able to demonstrate robust governance and control frameworks to avoid unwanted consequence.
Payments Review
Charles Radclyffe explores why technology might not be the universal force for good it has always assumed to be and why the sector should be thinking about technology governance to mitigate and manage potential harms.
Payments Review
With the rapid pace of innovation in the cryptoasset ecosystem, Ricardo Tordera discusses why regulation is now more paramount than ever and not just in the UK.
Payments Review
Paymentology’s Martin Heraghty explores how the lending landscape is changing and what this means for consumers.
Payments Review
Peter Harmston and Robert Dean at KPMG UK explore how AI can be adopted to have the biggest benefits for both business and customers.
ARYZE’s Jack Nikogosian discusses how private sector stablecoin initiatives could be the key to stability and innovation in the current financial system.
Lucinity’s Francisco Mainez outlines how technology can help businesses prepare and comply with the new rules, which are due to come into force in July.
Roberto Rivero of Lerex Technology explores the value branded cards could have for businesses.
Alex Mifsud of Weavr.io examines how technological advancements mean that customers can experience seamless banking across financial institutions.
Payments Review
Nikulipe’s Frank Breuss discusses the correlation between a country’s GDP and its accessibility to digital financial services, which suggests fintechs are key to financial inclusion in emerging markets.
Several payment initiatives are happening at the same time. If regulators and the industry fail to collaborate now, banks and other businesses face a challenging situation, according to Paul Horlock, chief payments officer at Santander UK.
March 2023
Embedded and invisible payments with reduced friction is on the horizon for retail payments, but players across the chain must not forget why there is friction. Santander’s chief payments officer Paul Horlock dives into what’s next.
March 2023
Open banking is leading the way for open finance and open data where robust open APIs and data management will be the cornerstones of success.
Spring 2023
With myths on digital currencies being a threat to financial freedom dominating social media, Dominika Duziak, of OneStep Financial, explains why government must address this narrative and discuss its advantages.
Spring 2023
Phil Mochan from Nomos Digital examines how cross-border payments is closely intertwined with cross-border liquidity and the challenges this poses for implementing CBDCs.
Mastercard is set to rollout Mastercom Collaboration in early 2023, an enhanced version of its current platform that enables merchants and acquirers to settle payment disputes before it becomes a formal chargeback.
Winter 2023
From a once ‘poor man’s card’ to paving the way for a new way to earn, Richard Ney examines how prepaid products are being used to underpin some of the slickest payment solutions and user experiences.
Winter 2023
Spencer Hanlan explores how the speed and efficiency of payments, particularly cross-border, could drive innovation to offset inflation. He sets out his top three predictions of 2023.

Membership

Merchant Community Membership

Are you a member of The Payments Association?

Member benefits include free tickets, discounts to more tickets, elevated brand visibility and more. Sign in to book tickets and find out more.